Industries / Construction and property
Insurance for construction and property
The contract sets the risk. The site decides whether it happens.
Contract works, liability and employees' compensation for developers, main contractors, fit-out firms and property owners.
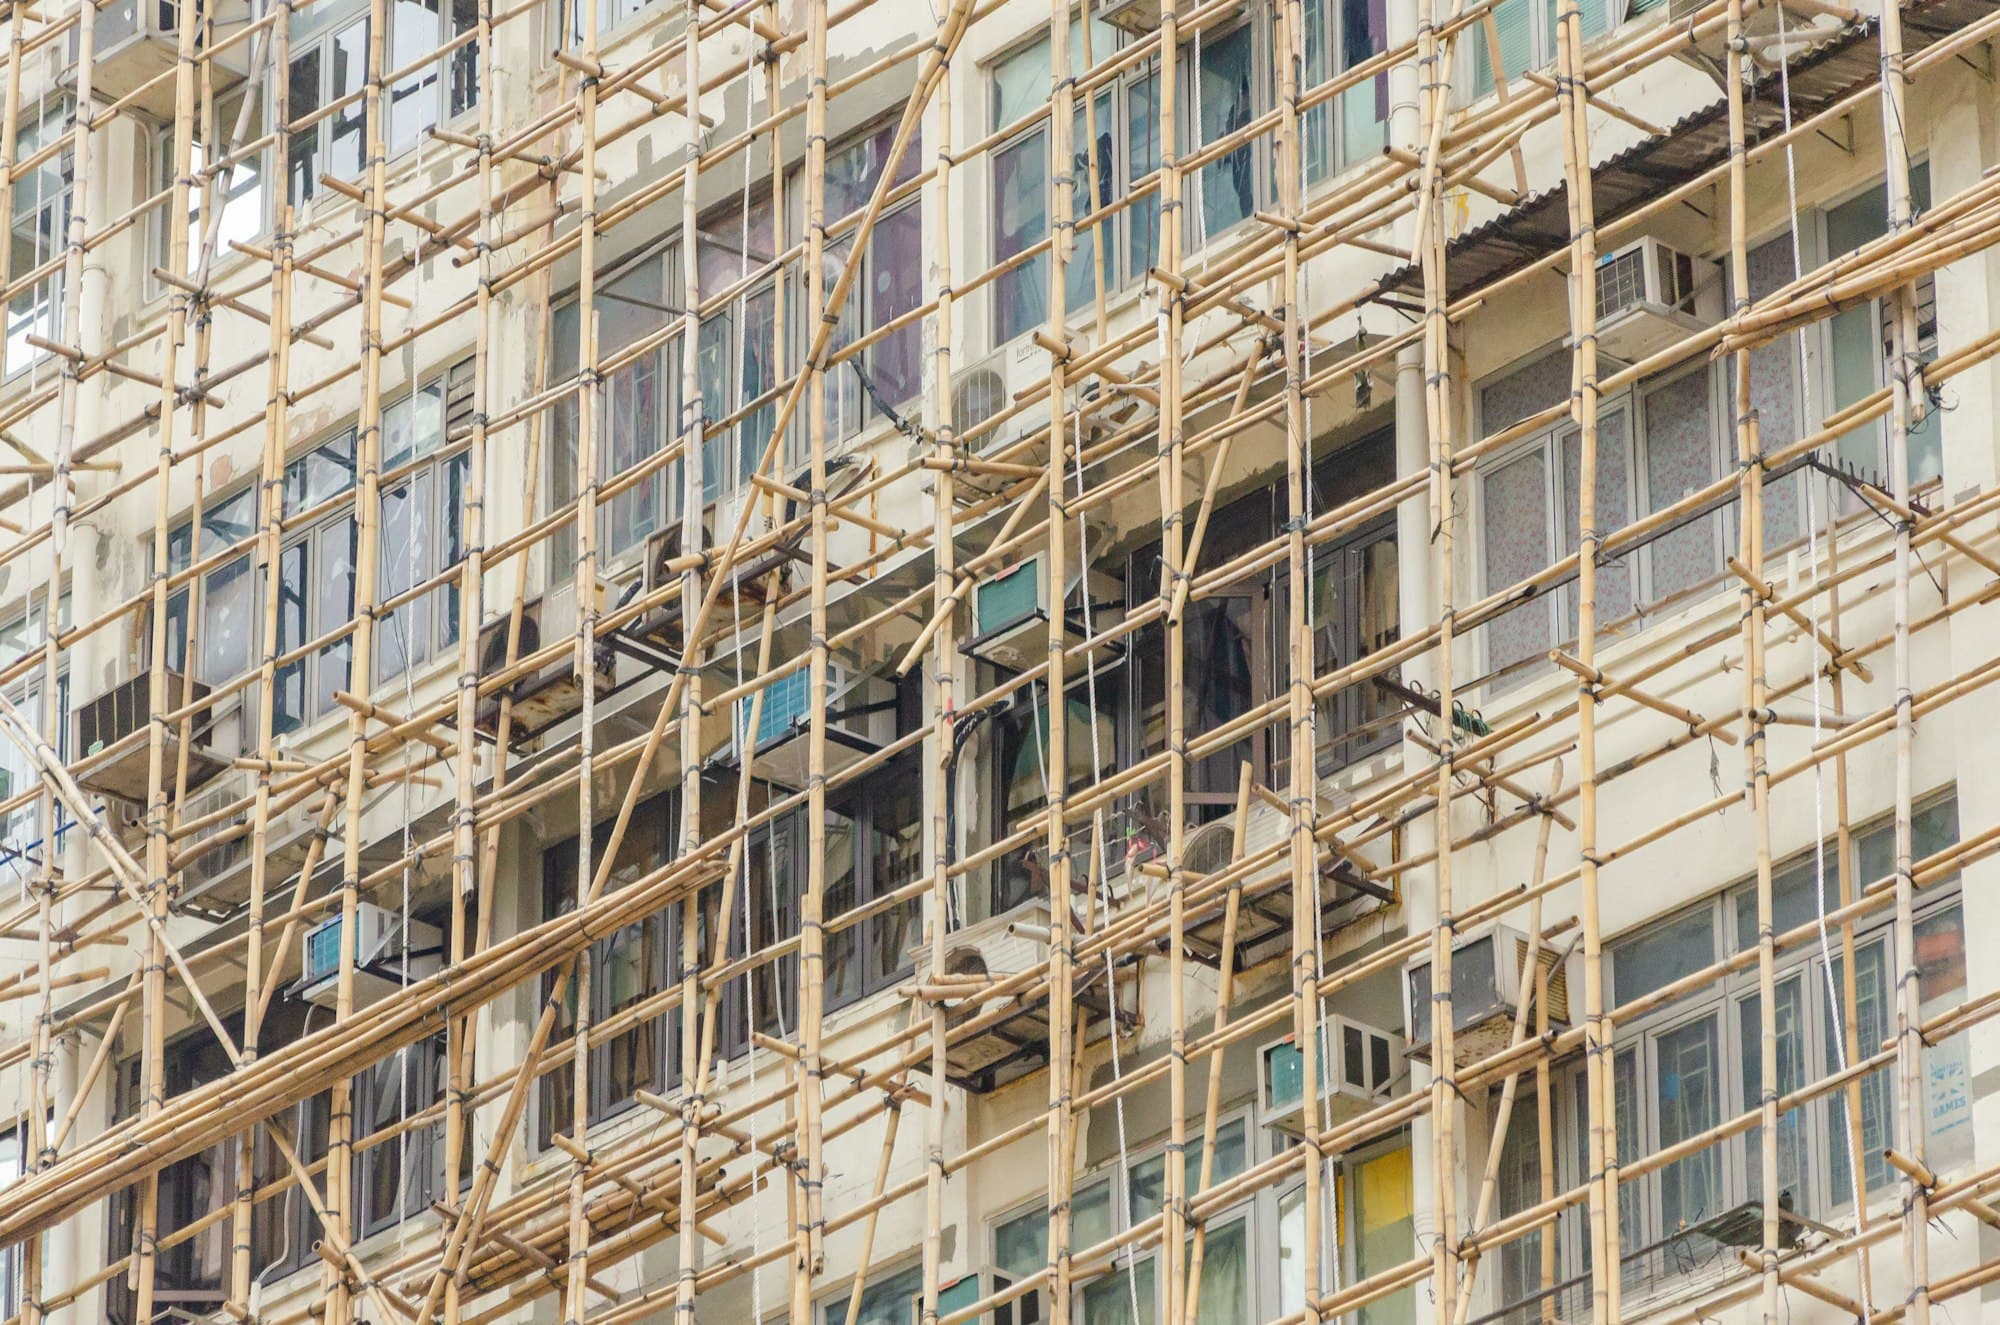
New South Sea for construction and property
- [—]
- Clients in this sector
- [—]
- Lines placed per client, median
- [—]
- Premium placed, HKD
01 Exposures
Named risks
Each risk, what it costs when it happens, and how the programme may respond.
Damage to the works
Typhoons, fire and collapse during construction fall on whoever the contract makes responsible.
Contract works cover written to the contract's insurance clauses.
Injury on site
Principal contractors can be liable for subcontractors' workers under Cap. 282.
Employees' compensation and liability that extend to subcontracted labour.
Damage to neighbouring property
Excavation and piling near existing buildings and rail lines carry high third-party exposure.
Third-party limits set from the site's surroundings, with existing structures declared.
Completed buildings
Owners need property and liability cover that takes over the day the contractor leaves.
Owner's property and liability in place on the handover date.
02 The programme
Typical insurance programme
The final structure depends on your contracts, sites and balance sheet. This is where the review starts.
- Construction all risksThe contract decides who insures the works. Read it before the market does.Line detail
- Employees' compensationCompulsory does not mean standard.Line detail
- Public and products liabilityLimits are bought for the worst claim, not the average one.Line detail
- Property and business interruptionThe sum insured is a number you choose. The indemnity period is a decision you make.Line detail
03 How we work
How we work
- 01ReviewStart with the exposures, not last year's schedule.
- 02PrepareThe underwriting file is the submission.
- 03MarketSelected markets, not a circulated list.
- 04BindThe policy is checked against the quote.
- 05ClaimsA named claims contact from the first notice.
“[Client quote, two sentences at most, on a renewal or claim New South Sea handled.]”
Questions
Should the owner or the contractor arrange the policy?
Owner-controlled programmes give one wording and one claims process. We review the contract and recommend before tender.
What is covered for defects?
That depends on the defects clause, usually LEG 2 or LEG 3. The choice should match the contract and the design risk.
Are subcontractors insured under our policy?
They can be named insureds. The contract and the policy must say the same thing.
Ready when you are
Send us the risk the last broker could not place.
Direct line[enquiries email]Monday to Friday, 9:00 to 18:00 HKT